VA Home Loans in Lake Oswego, Wilsonville, and Portland’s South Suburbs
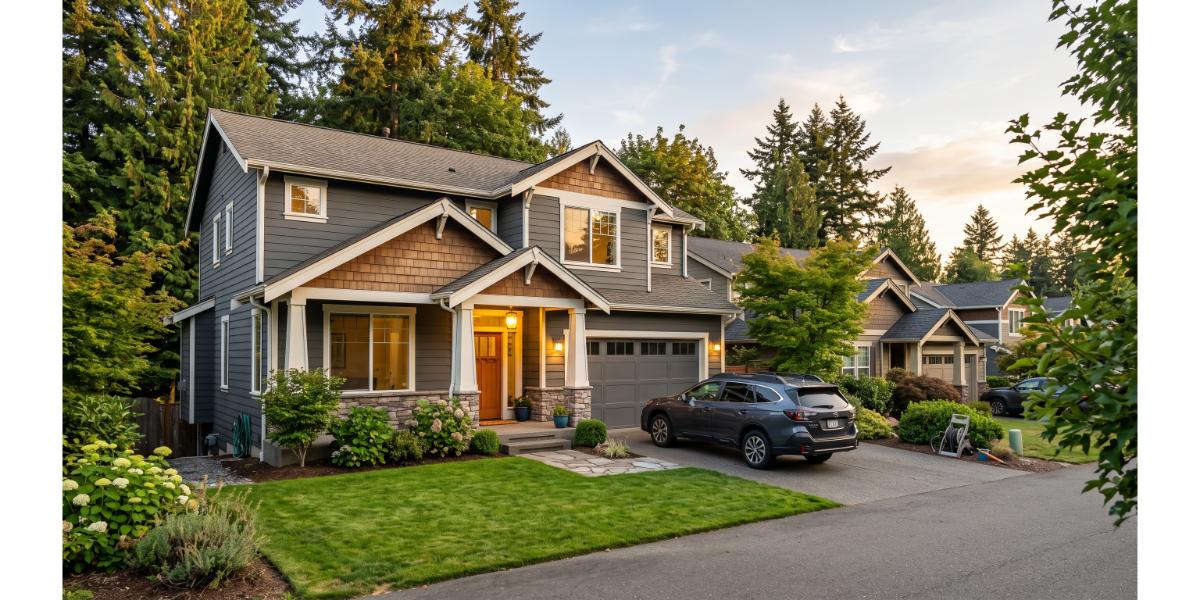
Many veterans assume a VA loan only works for a starter home. In the south Portland suburbs, that assumption can cost them real money.
A VA loan can be used in Lake Oswego, West Linn, Tualatin, Wilsonville, and Tigard the same way it can anywhere else. The question is how to use the benefit well in a market where prices and competition run higher than average.
What a VA loan does differently
VA loans are backed by the Department of Veterans Affairs and are available to eligible veterans, active-duty service members, and some surviving spouses.
The biggest differences from a conventional loan are that there is no monthly mortgage insurance and a down payment may not be required, depending on your entitlement and the price of the home.
Most borrowers pay a one-time VA funding fee, which can usually be rolled into the loan. Veterans with a service-connected disability rating are often exempt from that fee, so it is worth confirming your status early.
Entitlement matters more in higher-priced suburbs
Your entitlement is what determines how much you can borrow with no money down. Veterans with full entitlement generally are not capped by a county loan limit, while veterans who still have an active VA loan on another home may have reduced entitlement.
That difference matters in Lake Oswego and West Linn, where prices can push past what a reduced entitlement covers. In that case a partial down payment may still be needed. Knowing this before you tour homes keeps the search realistic.
Making a VA offer competitive
Some listing agents still worry that VA offers are harder to close. In practice, a well-prepared VA file closes on a normal timeline.
A few things help: a full pre-approval with income and entitlement already documented, a clear plan for the VA appraisal, and a broker who communicates directly with the listing agent so there are no surprises.
Because the VA appraisal also checks basic property condition, it helps to flag older homes with deferred maintenance before you write an offer, not after.
Why a broker helps with VA loans
VA guidelines are set by the VA, but each lender adds its own overlays on credit, debt ratios, and property types. Those overlays vary more than most buyers expect.
As an independent mortgage broker, Matt Jolivette can take one VA application to multiple wholesale lenders and match the file with the lender whose rules fit it best. That is especially useful for self-employed veterans or buyers with RSU or bonus income.
Matt is a Marine Corps veteran and a Certified Mortgage Consultant (CMC). He has helped veterans across Oregon, Washington, and Idaho plan purchases and refinances around their benefit.
Already own a home with a VA loan?
If you have a VA loan now, an Interest Rate Reduction Refinance Loan (IRRRL) may lower your payment with limited paperwork, and a VA cash-out refinance may be an option for larger projects. Whether either makes sense depends on your current rate, your balance, and how long you plan to stay.
Visit nwmortgagebroker.com or call (503) 545-8843 to start the conversation. Matt Jolivette, NMLS #90661. Associated Mortgage Brokers. Licensed in Oregon, Washington, and Idaho. Equal Housing Lender. All loans subject to credit approval and underwriting.
Matt Jolivette
Matt Jolivette, NMLS #90661, is a mortgage broker and co-owner of Associated Mortgage Brokers, company NMLS #86136. He began at the company as a loan processor in 2000, became a loan originator in 2001 and became a co-owner in 2011. He earned a Bachelor of Science degree in Finance from Portland State University in 2005.
Related Posts